

Cash Advance: Get 250 Fast
KOMPANIIA LORENS PP
- 4.7
- 970.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
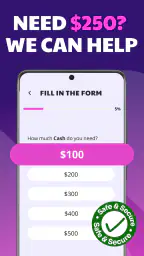
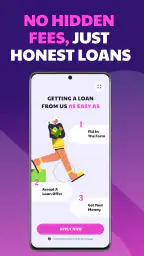
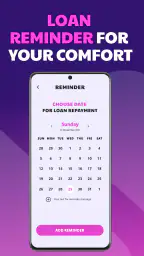
Cash Advance: Get 250 Fast Pros and Cons
Pros
- Fast application process with minimal paperwork
- Clear repayment terms shown before accepting an advance
- Helpful for covering unexpected short-term expenses
- Secure account verification helps protect personal information
- Simple interface makes loan details easy to review
Cons
- Approval and advance availability are not guaranteed
- Fees or interest can make repayment more expensive
- Eligibility may depend on income and banking history
- Repayment dates may be difficult for tight budgets
- Availability and terms can vary by location
 Analysis by All-app
When I look at a cash-advance app, I care less about the promise of speed and more about what happens when the process does not go smoothly. Cash Advance: Get 250 Fast is a free finance app from KOMPANIIA LORENS PP that is built around a straightforward borrowing journey. Its store summary points to simple steps and no subscription fees, while the short description keeps the focus on cash advance rather than trying to present itself as a full banking service.
That narrow focus is both its appeal and its main limitation. If you are trying to understand whether you can request short-term funds without committing to a recurring app subscription, the app is easy to place. If you are looking for budgeting tools, long-term money management, savings automation, or a replacement for your bank, I would look elsewhere. My experience with this kind of app is that the important questions are usually practical: can I complete the setup, what should I check before applying, and what do I do if the process pauses?
Where the experience usually gets stuck
The first point of friction is often not the cash-advance request itself but the information-gathering stage around it. A user may expect to open the app, enter a request, and finish immediately. In practice, finance apps commonly require careful entry of personal and financial details before they can evaluate an application. Even when the screens are simple, a small mismatch can slow the journey.
I recommend treating every field as a matching exercise. Use the same spelling and contact details you normally use for financial accounts, and avoid switching between old and current information halfway through the process. A shortened name, an outdated address, or a phone number that is not available for verification can create confusion. That is not necessarily a defect in Cash Advance: Get 250 Fast, but it is exactly the kind of avoidable friction that makes a simple workflow feel broken.
The next sticking point is expectation. The app presents itself as a cash-advance tool, not as a guarantee that every request will be accepted or completed instantly. A fast interface does not mean that every application produces an immediate result. Review steps, identity checks, account information, and external financial conditions can all affect the outcome. I would use the app with that distinction in mind: it may simplify the request, but it cannot remove every part of the lending process.
Another source of confusion is the phrase “no subscription fees.” I read that as an important difference from apps that charge simply for continued access to their interface. It should not be interpreted as a promise that borrowing is cost-free in every possible situation. Before accepting anything, I would read the displayed terms, repayment details, and any applicable charges carefully. A free download and no subscription fee are not the same thing as free credit.
The app is rated for Everyone, which makes its presentation approachable, but that age label should not be confused with suitability for every financial situation. Borrowing is still a serious decision. A friendly layout can make a process feel less intimidating, yet the responsibility to understand repayment remains with the person using it.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
What I would check before starting
Before opening a request, I would make sure the phone has a stable internet connection and enough battery to complete a financial form without interruption. I would also close other apps if the device is older or short on available memory. These are small steps, but losing a partially completed screen can be more frustrating than the original form.
I would keep the relevant personal and banking information nearby, but I would not paste sensitive details into notes, messages, or unverified pages just to speed things up. The safest workflow is to enter information directly into the official app interface and pause whenever a request is unclear. If a screen asks for something I do not understand, I would not guess merely to move forward.
It is also worth checking the app version before troubleshooting. Cash Advance: Get 250 Fast is currently listed as version 1.2.2 and supports Android 7.0 or later. That makes it usable on a wide range of Android phones, although compatibility on paper does not guarantee identical performance on every device. Older phones may handle transitions more slowly, while heavily customized Android systems can behave differently from the developer’s test environment.
My most useful preparation tip is to decide the repayment plan before submitting anything. Write down the amount you need, the date you expect to have money available, and the bills that must be protected first. This prevents the common mistake of focusing only on receiving funds while ignoring the later withdrawal or repayment pressure. If the repayment date would leave you short for rent, utilities, food, or essential transport, the app is probably not the right solution.
How I would recover from a stalled workflow
If a screen appears to freeze, I would first wait briefly rather than tapping the same button repeatedly. Repeated taps can create duplicate actions or make it harder to tell whether the request was submitted. I would note the last screen I reached, then leave the app and reopen it once. This simple reset is safer than repeatedly restarting the entire application process.
If the app closes, I would reopen it and check whether the previous step was saved before entering the same information again. I would avoid submitting multiple requests simply because the first response was slow. Duplicate attempts can create uncertainty about which request is active, and they make it harder to interpret later messages.
For a login or verification problem, I would check the phone number, email address, and device connection first. I would also confirm that automatic date and time settings are enabled, since incorrect device time can interfere with one-time codes and secure sessions. If a code does not arrive, I would wait before requesting another one and make sure messages are not being filtered or blocked.
When a form rejects information, I would reread the field rather than changing details randomly. A rejected entry may be caused by formatting, a mismatch with existing records, or a temporary service issue. Guessing can turn a correct application into an inconsistent one. The better approach is to use accurate information, save any reference or confirmation shown on screen, and contact the app’s official support route if the same problem continues.
There is a useful difference between a technical failure and a lending decision. A loading error, crash, or missing button is a technical issue. A message saying that a request cannot proceed is part of the financial process and should not be treated as something to bypass. I would never try to work around an eligibility result by creating repeated profiles or entering altered details.
Setup checks that save time later
My setup routine for this app would be deliberately boring. I would install it from the recognized app distribution channel, confirm that the developer name shown is KOMPANIIA LORENS PP, and avoid unofficial copies that imitate the same title. I would then read the opening screens carefully instead of rushing through them, especially wherever the app explains repayment, fees, or the handling of personal information.
I would keep notifications available while an application is active, but I would review what appears on the lock screen. Financial alerts can contain private information, so a user may prefer to hide message previews even if notifications remain enabled. This is a practical privacy choice rather than a feature claim about the app.
I would also avoid using public Wi-Fi for a financial application. A private mobile connection or trusted home network reduces the chance of exposing sensitive activity through an untrusted hotspot. If the app behaves differently on one connection, switching networks can help identify whether the problem is local connectivity rather than the application itself.
One non-obvious trade-off is the temptation to use an older phone because it is available and already set up. The minimum operating-system requirement is relatively broad, but an old device may have limited storage, outdated security components, or aggressive battery-saving settings. Those conditions can interrupt verification or background messages. If the app works on a newer device but not an older one, I would treat the device environment as a likely factor before assuming the service is unavailable.
When the app is not the cause
Not every delay belongs to the app. A weak connection can make a form appear stuck, and a bank or payment service may be temporarily unavailable even while the app itself opens normally. Scheduled maintenance, account restrictions, incorrect financial details, or an expired verification message can all produce a disappointing result without indicating that the interface is defective.
This distinction matters because reinstalling an app does not repair an external account problem. I would only clear app data or reinstall after recording any relevant confirmation details and making sure I can sign in again. Reinstalling too early can remove local session information and make a straightforward support conversation more difficult.
Device security settings can also interfere with normal use. A phone with an incorrect time zone, disabled notifications, restricted background activity, or extremely limited storage may prevent messages or screens from updating properly. I would check those basics before changing advanced settings. I would not disable security protections or install unknown tools to force a financial workflow to continue.
There is also a human cause: urgency. When money is tight, it is easy to skim a disclosure, accept a term without reading it, or submit an application several times. I think the app should be judged partly by how well it supports calm decisions, but the user still needs to slow down. If the request feels confusing, stop and review the exact amount, repayment obligation, and any displayed cost before proceeding.
How it compares with ordinary alternatives
Compared with asking a bank for an overdraft or personal loan, Cash Advance: Get 250 Fast appears more focused on a short, app-based request rather than a broader banking relationship. That can be convenient for someone who does not want a new budgeting platform or a recurring membership. The trade-off is that a dedicated cash-advance tool may offer less context about a person’s overall finances than a bank account or budgeting service.
Compared with borrowing from a friend or family member, the app gives the process a more formal structure, but it also introduces the need to understand financial terms and repayment consequences. A personal loan from a bank may be more suitable for a larger planned expense or a longer repayment horizon. For a small, temporary gap, a cash-advance app may feel more direct, but directness should not be mistaken for affordability.
Compared with a budgeting app, this product solves a different problem. Budgeting software helps identify where money is going and may prevent the next shortfall; this app is aimed at requesting an advance. If your recurring issue is that bills exceed income every month, borrowing repeatedly will not fix the underlying gap. In that situation, I would choose a budgeting tool, speak with a financial counselor, or negotiate bills before relying on advances.
The app’s free status and lack of subscription fees make it easier to consider than a service that charges just to remain active. Still, I would compare the complete cost and repayment conditions with alternatives rather than stopping at the download price. The best option is the one that solves the immediate need without creating a larger problem at the next payday.
Who will find it useful, and who should skip it
I can see the appeal for an Android user who needs to explore a short-term cash advance through a focused interface and wants to avoid a recurring subscription. The app has attracted a substantial audience, with over one hundred thousand installs, and its average rating is 4.7 from around twenty-four thousand ratings. Those figures suggest that many people find the experience accessible, although they cannot predict whether a particular request will be approved or whether the terms will suit an individual budget.
I would consider it for a one-off emergency only after checking the full repayment obligation. A realistic example would be discovering that an essential bill is due before a regular paycheck arrives. I would open the app, verify my details, review the amount and repayment information, and decide whether the next paycheck could cover the advance without affecting essentials. If the answer were uncertain, I would not submit simply because the interface made the request feel quick.
I would skip it if I needed a large, long-term loan, detailed spending analysis, investment tools, or a permanent replacement for a bank account. I would also skip it if my income is already committed to existing debts. An advance can bridge timing; it is a poor fit for a continuing deficit.
The app was released on July 12, 2023, and its current listing identifies it as a finance application rather than a game or general utility. That context matters: the right way to evaluate it is through clarity, responsible use, and recovery from interruptions, not through entertainment value or the number of visible features.
My practical verdict
Cash Advance: Get 250 Fast is most convincing when treated as a focused tool for exploring a short-term advance, not as an all-purpose financial companion. I like the simple positioning, the free download, and the absence of a subscription fee. I also appreciate that the app does not need to be judged as a complicated money-management suite when its purpose is narrower.
My caution is equally clear: a smooth request screen does not remove the cost, eligibility, verification, or repayment questions that matter most. The strongest workflow is to prepare accurate information, use a trusted connection, submit only once, record confirmations, and separate technical problems from financial decisions. Those habits make the experience less stressful and reduce the risk of turning a temporary cash gap into repeated borrowing.
My recommendation is conditional: use it only when you understand the complete obligation and have a realistic repayment plan. It may suit someone seeking a focused cash-advance route without a subscription, especially on an Android device that meets the operating-system requirement. It is not the right choice for ongoing financial shortfalls, major borrowing, or anyone who needs budgeting and banking features in the same place.
In short, I would keep this app in the “consider carefully” category rather than recommending it automatically. Its practical value comes from a narrow, approachable workflow, while its risks come from the financial decision surrounding that workflow. If you can separate those two things and read every term before accepting, it is worth examining. If you need a broader or more predictable financial solution, a bank, budgeting service, or non-borrowing alternative may be better.
Frequently Asked Questions
What is Cash Advance: Get 250 Fast, and how does it work?
Cash Advance: Get 250 Fast is a financial app designed to help users explore short-term cash advance options through a mobile device. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can assess eligibility. The app may connect you with third-party lenders or providers, so approval, loan amounts, fees, and repayment terms can vary.
Can everyone receive a $250 cash advance through the app?
No. Downloading or completing an application does not guarantee approval or a specific advance amount. Eligibility usually depends on factors such as your income, employment status, banking activity, identity verification, state of residence, and the requirements of participating providers. Some users may qualify for less than $250, while others may not receive an offer at all. Always review the final terms before accepting.
How quickly can I receive money after applying?
The app promotes fast access, but the actual delivery time depends on verification, approval, the selected provider, your bank, weekends, holidays, and the transfer method available to you. Some transfers may arrive quickly, while standard bank deposits can take longer. Any instant-transfer option may involve an additional fee, so check the timing and cost shown before confirming a request.
What fees, interest, or repayment conditions should I check?
Before accepting an offer, carefully review the annual percentage rate, finance charges, origination or subscription fees, expedited-transfer costs, late-payment penalties, and the total repayment amount. A cash advance can be expensive if it is not repaid on time. The app may present offers from different providers, meaning terms are not necessarily identical. Read the agreement and confirm the due date.
Is Cash Advance: Get 250 Fast safe to use, and what information does it require?
As with any financial application, use caution before submitting sensitive information. The service may request details such as your full name, address, identification information, income, employer, bank account, and contact details. Download it only from an official app store, check the developer and privacy policy, and avoid sharing passwords or verification codes. If the requested permissions or terms seem excessive, stop and investigate further.


